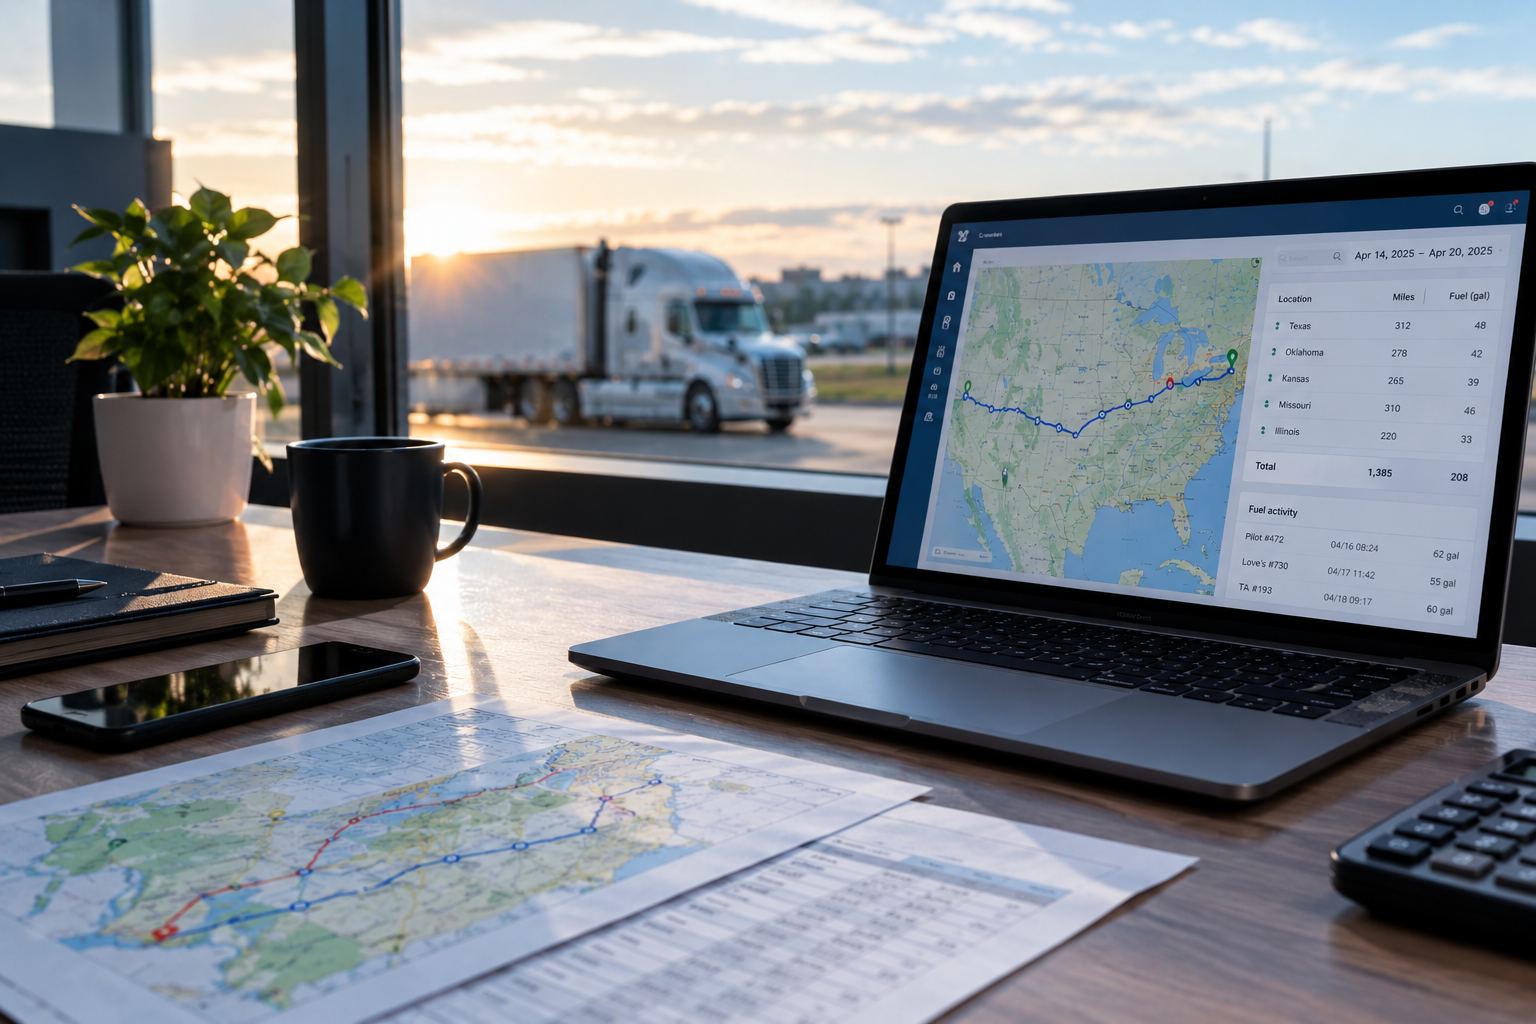
Meta Description: Learn about common IFTA reporting mistakes, including mileage, fuel records, jurisdiction errors, and missing documentation, and how to avoid them.
Common IFTA reporting mistakes
IFTA reporting requires trucking companies to keep track of mileage, fuel purchases, and operations across different jurisdictions. For carriers operating across multiple states and provinces, even a small data error can make the quarterly reporting process more difficult.
The problem is not always the IFTA calculation itself. In many cases, mistakes start earlier — with incomplete records, incorrect mileage, fuel data assigned to the wrong vehicle, or information that does not match across different systems.
Understanding the most common IFTA reporting mistakes can help carriers organize their records and make quarterly reporting easier.
What is IFTA reporting?
The International Fuel Tax Agreement (IFTA) is an agreement among participating U.S. states and Canadian provinces that simplifies fuel tax reporting for qualified motor carriers operating in multiple jurisdictions.
Instead of filing separate fuel tax returns with every jurisdiction where a carrier operates, the carrier generally files through its base jurisdiction.
IFTA returns are generally filed quarterly. IFTA, Inc. maintains the current Articles of Agreement and other official IFTA manuals used by participating jurisdictions.
A carrier's IFTA reporting process typically involves information about:
- Total distance traveled
- Distance traveled in each jurisdiction
- Taxable and non-taxable miles where applicable
- Fuel purchased
- Tax-paid fuel
- Fuel consumption
- Applicable jurisdictional tax rates
Because several types of information must work together, errors can occur at multiple points in the process.
1. Reporting incorrect mileage
One of the most important parts of IFTA reporting is accurate distance information.
A carrier needs to know not only how many miles its vehicles traveled, but also how those miles are allocated among jurisdictions.
Problems can occur when mileage records are:
- Incomplete
- Duplicated
- Assigned to the wrong vehicle
- Based on estimates without adequate supporting records
- Missing trips or portions of trips
- Inconsistent with other fleet records
IFTA audit guidance identifies incorrect distance reporting and missing records among the issues that can result in audit adjustments.
For this reason, carriers should review mileage before preparing the quarterly return instead of discovering inconsistencies after the report has already been submitted.
2. Using ELD mileage without checking the data
ELDs automatically record certain vehicle and operational information, including vehicle miles and location information. However, FMCSA specifically notes that mileage tracking for tax reporting purposes is not part of the ELD data required under 49 CFR Part 395. A manufacturer may offer mileage or tax-reporting functionality as part of a broader fleet-management package.
That distinction is important.
An ELD can provide useful mileage and location data, but carriers should not automatically assume that every number produced by an ELD is ready to be used as the final IFTA figure.
Before using the data for IFTA, carriers should review how the system handles:
- Jurisdiction changes
- Vehicle mileage
- Trips
- Unusual routes
- Missing data
- Vehicle assignments
- Corrections
The ELD can be a valuable source of information, but the IFTA reporting process still requires proper review.
3. Mixing up total miles and jurisdiction miles
Another common mistake is confusing total fleet mileage with mileage traveled in individual jurisdictions.
For example, a truck might travel through several states during one trip. The carrier cannot simply use the truck's total mileage as the mileage for every jurisdiction.
Instead, the mileage needs to be allocated appropriately.
A basic reporting structure might look like:
Total miles → Jurisdiction miles → Taxable miles → IFTA calculation
If the jurisdiction-level mileage does not reconcile with the total mileage, the carrier should investigate the difference before filing.
IFTA audit guidance specifically identifies variances between quarterly jurisdictional distance and total distance as information that may warrant review.
4. Missing or incomplete fuel records
Mileage is only one side of the IFTA calculation.
Fuel records are also important, particularly when a carrier is claiming tax-paid fuel.
A common problem is missing documentation for fuel purchases.
Examples include:
- Missing fuel receipts
- Incomplete fuel card records
- Incorrect vehicle or unit numbers
- Fuel purchases that cannot be matched to the correct vehicle
- Missing information for cash fuel purchases
- Duplicate transactions
IFTA audit materials emphasize the importance of adequate records and documentation for fuel and distance reporting.
Carriers should therefore keep fuel records organized throughout the quarter instead of trying to reconstruct everything when the filing deadline approaches.
5. Assigning fuel purchases to the wrong truck
Fuel transaction data can contain errors even when the purchase itself was legitimate.
For example, a driver may enter the wrong unit number when purchasing fuel, o